
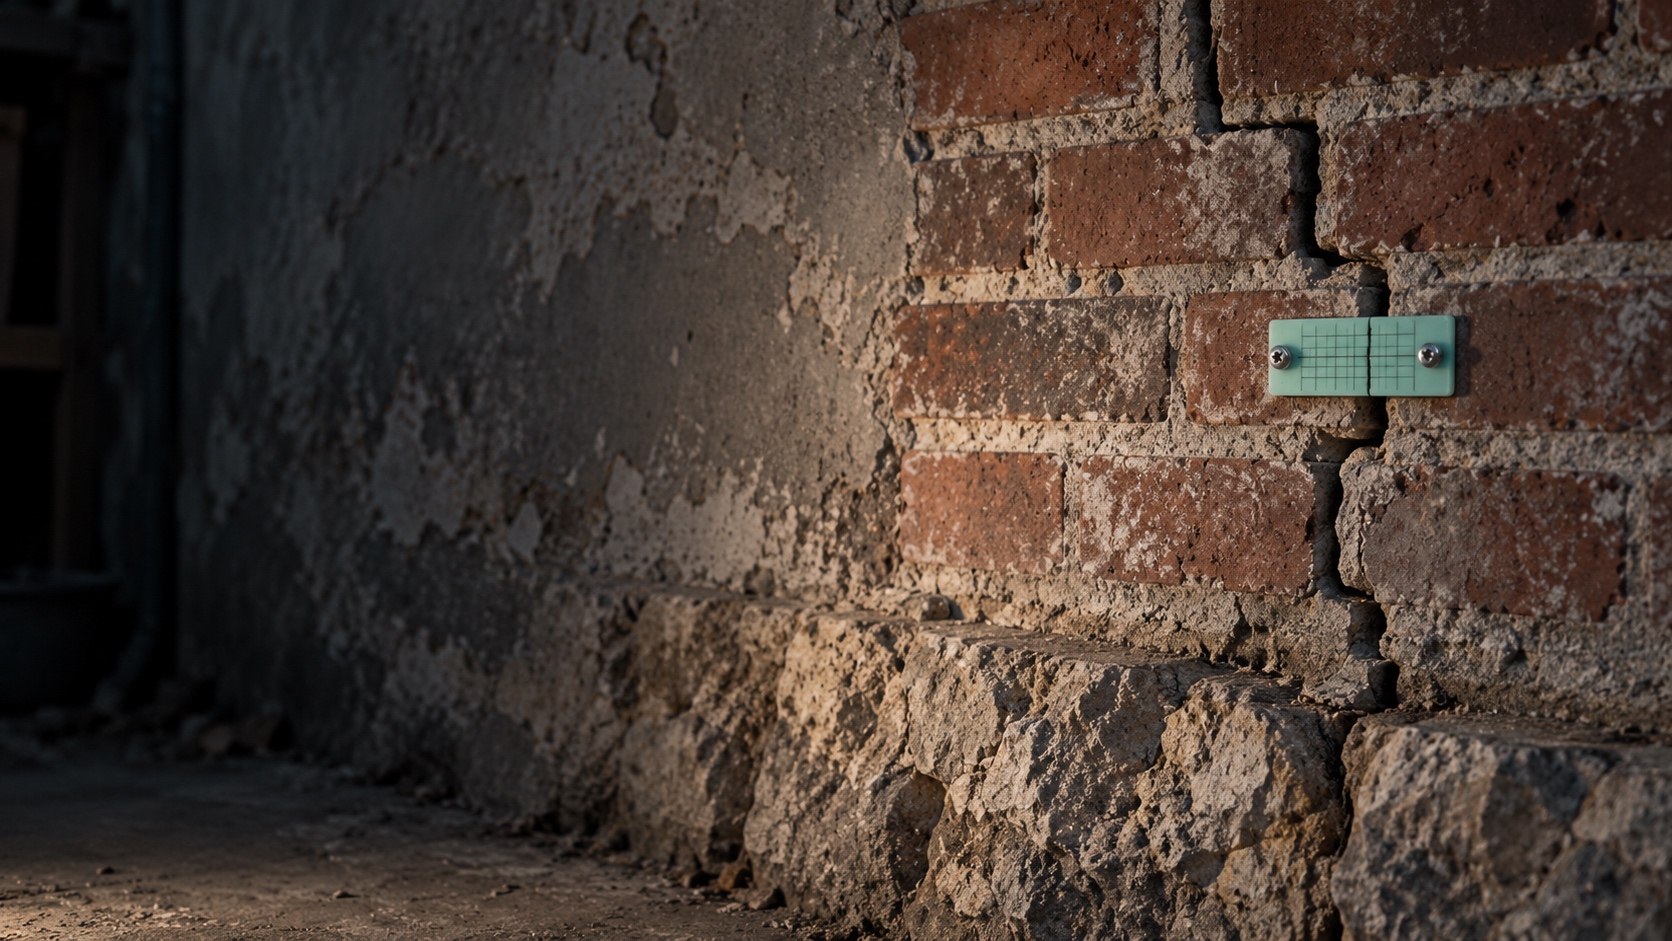
- Nearly every Kentucky policy excludes earth movement from any cause, and most introduce the exclusion with a clause that reaches any other cause that contributed. If your denial cites it, the letter is probably quoting the policy correctly. Whether it describes your house is the question.
- In the 37 Kentucky Mine Subsidence Insurance Fund counties, the coverage is supposed to be written into your policy unless you waived it in writing. If it isn't on your declarations page, the first question is whether a signed waiver exists — and who signed it.
- On policies written or renewed since January 1, 2025, the Fund's limits are $500,000 per structure, plus up to $50,000 in living expense on a home, for collapse of a man-made underground mine — not sinkholes, surface mining, or earthquakes.
- Kentucky puts a 12% interest clock on a claim the carrier won't settle in good faith, running from 30 days after the carrier has notice and proof of the claim — and a formal, sworn proof of loss is the document that puts that date beyond dispute. On a foundation file that has sat in "monitoring" long after the ground stopped moving, it is the lever.
- If your foundation claim was denied as earth movement, or has sat in monitoring for a year, send us the policy, the denial, and the engineering and we'll tell you whether the file is stuck or just slow. Our KY residential and commercial property damage work is generally on contingency — we only get paid from the recovery, not your pocket.
The letter that denies your foundation claim will quote an exclusion that is in nearly every Kentucky homeowners and commercial policy, and it will quote it accurately. Earth movement — sinkholes, subsidence, settling, cracking — is excluded whether nature or people caused it. What the letter will not tell you is whether those words describe what happened under your house, or whether a coverage you were entitled to was ever written into your policy at all.
If you're in Harlan, Perry, Letcher, or Floyd County in the east, or Hopkins, Muhlenberg, or Henderson in the west, you live over mined-out ground, and your question is specific: is the Mine Subsidence Fund endorsement on your declarations page, and if not, why not. If you're in Bowling Green or the Pennyroyal, where the limestone dissolves, or anywhere on a slab that has started to drop, the question is different: did something sudden happen, or has the ground been settling since the house was built.
This article walks through what the exclusion leaves alone, what should be on a policy in a Fund county, when a mine claim's monitoring stops being normal, the four situations we at Property People Law see most on Kentucky foundation files, and the interest clock Kentucky puts on a carrier that won't settle. We handle these claims across the state from Louisville, for policyholders only. Every policy is different, every claim turns on its own facts.
What the Exclusion Says, and What It Leaves Alone
Read the exclusion in your own policy first, because the forms vary and the exceptions are where a claim lives. It names earthquake, landslide, mudflow, subsidence, and sinkhole, and in most Kentucky forms it is introduced by a sentence saying the insurer does not cover loss caused by those things "regardless of any other cause or event contributing concurrently or in any sequence to the loss." That lead-in is an anti-concurrent-causation clause — the sentence the carrier will quote when it denies the burst pipe and the ruined floor along with the foundation. Courts have generally given clauses like it effect; what it reaches on a particular set of facts is a question of wording and evidence, and it gets argued.
Three carve-outs sit elsewhere in most forms and do most of the work on a disputed claim. The sudden and accidental discharge of water from a plumbing system is a covered peril, and the tear-out needed to repair the system is usually covered with it — both riding on an exception the policyholder has to establish. Collapse coverage, in most forms, pays for an abrupt falling-in of the building from the causes it lists, and some Kentucky policies add a sinkhole-collapse endorsement for sudden settlement into a void beneath the structure. Fire that follows earth movement is covered as fire.
None of those reach gradual settling, and that is where most Kentucky foundation claims die. A crack that widened over three winters, a slab sinking since the house was built — excluded, and the denial is right. The claims worth your time are the ones where something sudden happened and the carrier has called it gradual: a pipe let go, a void opened, a mine roof came down.
What Should Be on Your Policy in a Mine Subsidence Fund County
The Kentucky Mine Subsidence Insurance Fund exists because the exclusion is in every policy and coal country sits on hollow ground. It works through your own insurer, and the rule in its counties is specific: an insurer writing property coverage on a structure there is supposed to include the mine subsidence endorsement, and may leave it out only if you waived the coverage in writing — and it cannot require that waiver as a condition of the policy. So if the endorsement isn't on your declarations page, the question is whether a signed waiver exists, when, and by whom.
Check the county first. The Fund operates in 37 counties — Bell, Boyd, Breathitt, Butler, Carter, Christian, Clay, Daviess, Edmonson, Elliott, Floyd, Greenup, Hancock, Harlan, Henderson, Hopkins, Jackson, Johnson, Knott, Knox, Laurel, Lawrence, Lee, Leslie, Letcher, Martin, McCreary, McLean, Morgan, Muhlenberg, Ohio, Owsley, Perry, Union, Webster, Whitley, and Wolfe — and the coverage can't be written on a structure outside them; not every coal county is on the list. If yours is, the endorsement should be on the policy, and the Department of Insurance's current guide puts what it pays at up to $500,000 per structure, plus up to $50,000 in additional living expense on a home, for collapse of a man-made underground mine; a policy written before 2025 can carry the earlier limits until it renews. Sinkholes, surface mining, and earthquakes are not what it's for.
A Fund claim runs on its own track. You report it to your insurer, which involves the Fund; a licensed civil engineer has to confirm that a mine, and not something else, is under the movement. Ground that is still moving isn't repaired until it stops, and the Department's consumer materials describe a monitoring period that can run a year or longer. That is the program working, not a carrier stalling — and it is the reason to put every measurement and every month in writing from the first visit, because the day the ground stops moving is the day the file's silence starts to mean something else.
When the Ground Has Stopped Moving and the File Hasn't
Monitoring has an end. The measurements go flat, the crack stops widening, the gauges hold for months — and the file should move to a repair design and a payment. When it doesn't, you are no longer waiting on the ground; you are waiting on the carrier, and Kentucky gives you a way to say so that changes the carrier's arithmetic.
Ask, in writing, for the monitoring data and the standard the carrier is using to decide the movement has stopped, and ask for a date. The next step owners commonly take is a formal proof of loss — the sworn statement of what was lost and what it will cost to repair, supported by the engineering and a contractor's scope. In Kentucky that document is not paperwork. The interest statute's clock runs from the carrier's receipt of notice and proof of the claim, and a sworn proof of loss is what puts that receipt, and that date, beyond argument — on a file that has sat a year after the measurements went flat, it is the most useful thing you can send.
The slab-leak claim — a line that failed under the house and washed the soil out from under the floor — is a different animal. The short Kentucky version: it is won on a timeline and an engineer, and the formal proof of loss matters there for the same reason it matters on a mine file.
Four Situations We See on Kentucky Foundation Files
Your County Participates and the Endorsement Isn't on the Policy
Ask the agent and the carrier, in writing, for the signed waiver. If there isn't one, the coverage was supposed to be in the policy, and the conversation is about why it wasn't. If there is one and you don't remember signing it, ask for a copy before you accept the answer. Bring us the policy history; this is a question with a document behind it.
The Carrier Has Been Monitoring for a Year
Monitoring is legitimate while the ground is moving and the measurements say so. Ask for the data. If the readings have been flat for months and no repair has been designed, the usual next step is a formal proof of loss with a date on the request; the interest clock below is why that document matters more than another phone call.
The Denial Says Earth Movement and Your Plumber Says Leak
That is the sequence fight, and it is won or lost on the engineering. Get your own engineer, give them the plumber's report, the leak-detection findings, and the water bills, and ask whether the settlement pattern follows the washout. A report that says it does is the document that forces the carrier to argue the facts instead of quoting the form.
The House Is on a Hill and the Crack Has Been There for Years
Seasonal settling is excluded, and we'd rather say so in the first call than after an engineer has billed you. In a Fund county, though, "just settling" is not the end of the inquiry — mined ground moves slowly too, and a structure with the endorsement on the policy is entitled to an engineer's look at whether a mine is under it before anyone calls it settling.
The Clock Kentucky Puts on a Stalled Claim
Neither of Kentucky's two rules touches a carrier that read the exclusion correctly and said so. Both are aimed at the carrier that had a covered loss in front of it and would not act. Under Wittmer v. Jones (1993), a bad-faith claim requires three things: that the policy covered the loss, that the carrier denied or refused payment without a reasonable basis, and that the carrier either knew it had no reasonable basis or acted with reckless disregard of whether it did. When those elements are met, Kentucky law may allow attorney's fees, consequential damages, and punitive damages.
The sharper tool on a foundation file is the interest statute. Under KRS 304.12-235, when the carrier fails to make a good-faith attempt to settle, the settlement value bears interest at 12% per year beginning after the expiration of 30 days following the carrier's receipt of formal proof of loss. The clock runs from the carrier's receipt of notice and proof of the claim, and a sworn proof of loss is the cleanest way to fix that date — which is why, on a file that has sat in monitoring long after the ground stopped moving, it is the document that changes what waiting costs the carrier.
Most foundation claims never get near either rule; they are decided on the engineering. But a file with flat measurements, a competent engineer's report, a formal proof of loss, and a year of unanswered letters is the file these rules were written for. The three Wittmer elements, and what satisfies them, are the subject of our Kentucky bad-faith guide.
How Property People Law Approaches Kentucky Foundation and Mine Subsidence Claims
On a mine file we start with three documents: the declarations page, for the endorsement; the agent's file, for the waiver or its absence; and the engineer's measurements, for whether the ground is still moving. On a slab or sinkhole file we start with the exclusion and its lead-in clause in your form, then the denial against them, and we say which it is — gradual settling the policy excludes, or something sudden the carrier has called gradual. If a report from the carrier's engineer already exists, we read it for the measurements it never took.
When the engineering supports coverage and the carrier won't act, we bring in the engineer the file needs, prepare and serve the formal proof of loss, and press the claim with the interest clock running. Our Louisville office handles these files across Kentucky; we represent policyholders, never carriers.
Our KY residential and commercial property damage work is generally on contingency — we only get paid from the recovery, not your pocket. Past results in other cases don't guarantee outcomes in any new matter, and every claim turns on its own facts.



