
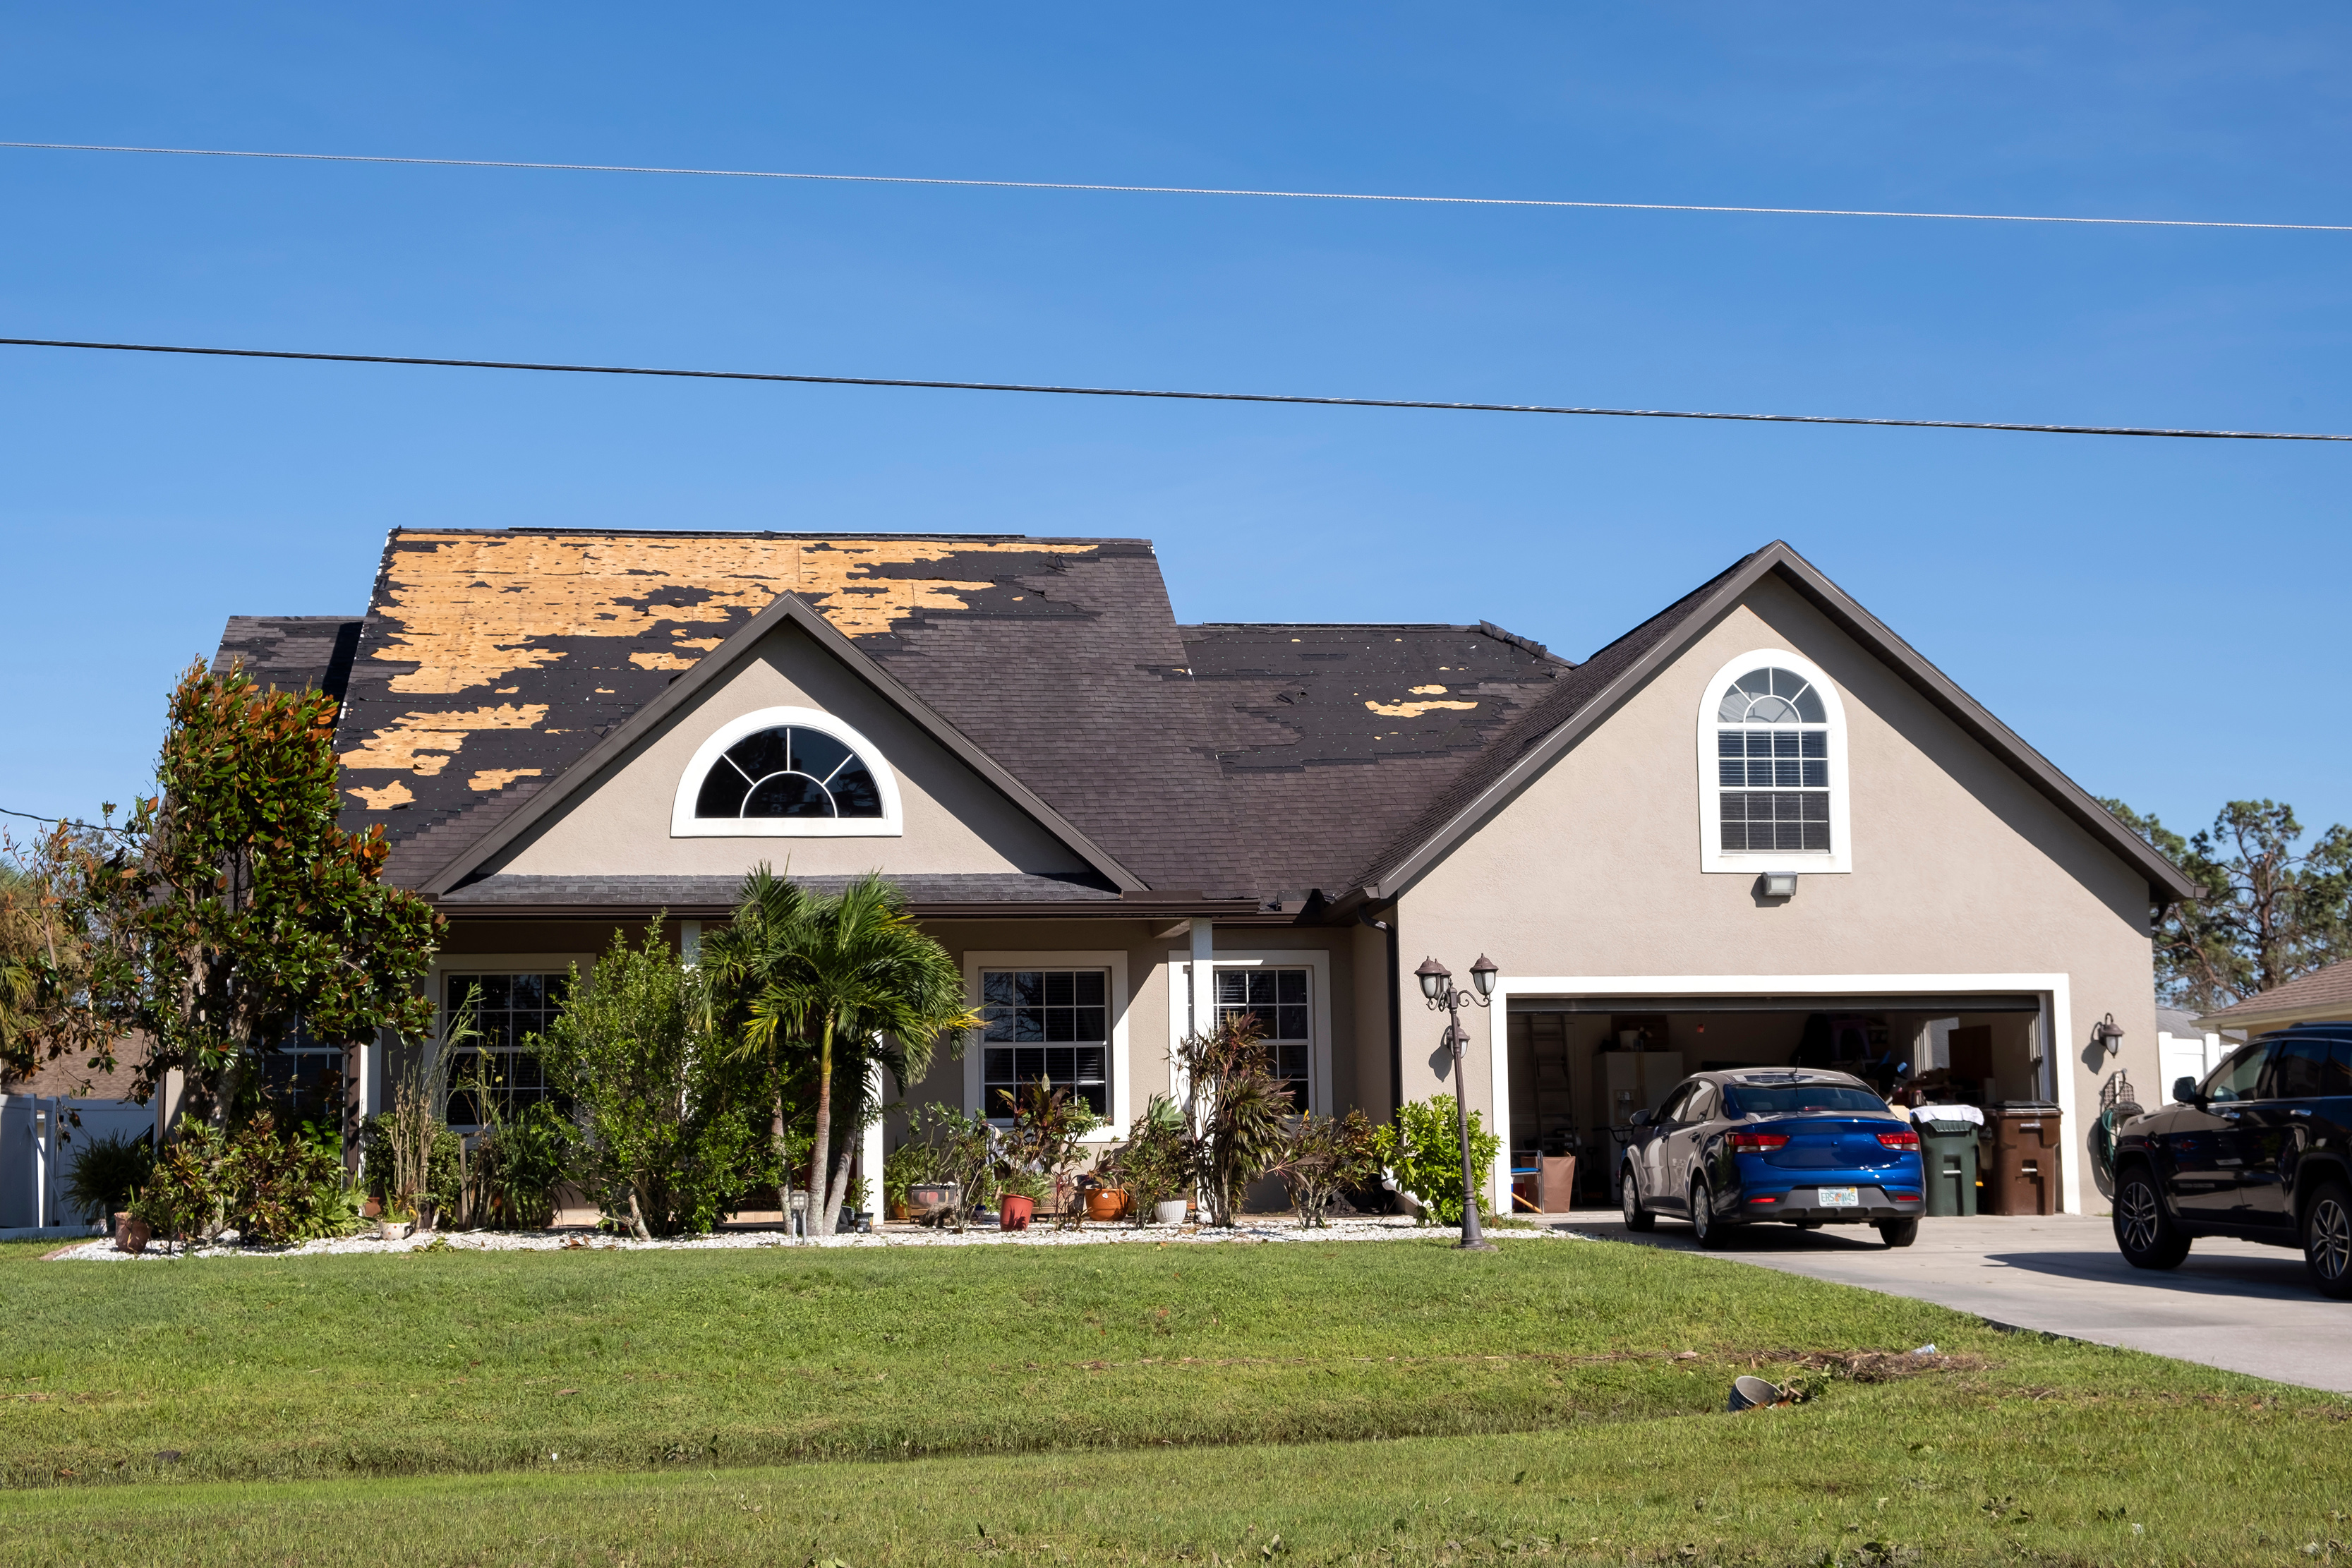
- Claims become complex when there are multi-cause losses (hurricane + flood, fire + water + mold), large dollar amounts ($100K+), commercial property issues (business interruption), subrogation against third parties, or expert disputes over causation and scope.
- Concurrent causation is Florida's most-litigated complex claim issue. Insurers use anti-concurrent causation (ACC) language to defeat coverage; policyholders use the "efficient proximate cause" doctrine to preserve it. Outcome depends heavily on specific policy language and facts.
- Hurricane wind (covered) vs. flood/storm surge (NOT covered) is the defining Florida coastal coverage dispute. Engineer testimony, wind speed data, and damage-pattern analysis often decide it.
- Large losses trigger different procedures: senior adjusters, routine EUO requests, sworn proof of loss demands, engineering investigation, and reservation of rights letters. Statements made carelessly become fatal to the claim.
- Complex claims that go to litigation take 12–24 months and become expert witness battles. Get legal counsel and expert support early — the insurer already has theirs.
What makes a Florida property damage claim "complex"
Most property damage claims follow a recognizable pattern: damage happens, the adjuster inspects, the insurer estimates, and the parties either agree on a number or negotiate to one. Complexity enters when the basic framework breaks down. The damage has multiple causes, or the dollar figure is large enough to trigger different procedures, or the property is commercial rather than residential, or there are multiple parties with competing interests in the same loss.
The categories of complexity in Florida property damage claims tend to be:
- Multi-cause / concurrent causation losses (hurricane wind + flood, fire + smoke + water damage from suppression, freeze + water + mold)
- Large losses typically over $100,000–$250,000 that trigger heightened scrutiny, large-loss adjusters, and frequent EUO requests
- Commercial property claims with business interruption, extra expense, and business personal property components
- Subrogation disputes where the insurer pursues recovery from a third party
- Multiple-party disputes involving contractors, neighbors, HOAs, or municipalities
- Expert witness battles over causation, scope, or cost
- Coverage disputes that turn on specific policy interpretation, often with significant case law on each side
Each of these requires more legal sophistication than a straightforward $30,000 hail claim. The procedural rules, the expert work, and the litigation strategy all change.
Concurrent causation: Florida's most-litigated complex-claim issue
The single most common complex claim issue in Florida is concurrent causation — when a covered cause and an excluded cause both contribute to the loss. The classic example is a hurricane that brings both wind (covered) and storm surge or flooding (excluded under standard homeowners policies). Another common pattern: fire (covered) followed by water damage from suppression efforts (covered) followed by mold (often excluded or sublimited).
Florida courts have spent decades refining the concurrent causation analysis. The two competing doctrines:
Efficient Proximate Cause
Under this doctrine, coverage turns on which cause was the dominant or efficient cause of the loss. If the dominant cause is covered, the entire loss is covered even though an excluded cause also contributed. The Florida Supreme Court has addressed this in several leading cases, and the specific facts of the loss matter enormously.
Anti-Concurrent Causation (ACC) Language
Many policies now include anti-concurrent causation language designed to defeat the efficient proximate cause doctrine: "We will not pay for loss caused directly or indirectly by any of the following. Such loss is excluded regardless of any other cause or event that contributes concurrently or in any sequence to the loss." Whether ACC language is enforceable in Florida depends on the specific clause, the loss facts, and the way the policy is written.
For complex claims involving concurrent causes, the legal analysis is often the most valuable part of the case. Properly framing which cause was efficient, properly applying or defeating ACC language, and properly allocating between covered and excluded components frequently determines whether the policyholder gets paid $0 or full policy limits.
Hurricane wind vs. flood: the defining Florida coverage dispute
Hurricane losses produce more concurrent causation disputes than any other category in Florida. The standard rule:
- Wind damage is covered by your homeowners policy
- Flood damage is NOT covered by homeowners — it requires separate flood insurance through the National Flood Insurance Program (NFIP) or a private flood carrier
- Storm surge is legally classified as flood, not wind — a critical distinction for coastal properties
When a hurricane causes substantial damage to a coastal property, the insurer's first move is often to classify the damage as flood (no homeowners coverage) rather than wind (covered). The policyholder's counter is to show that wind preceded and caused damage independent of any later flooding. The proof issues are technical and expert-heavy:
- Wind speed and direction data from the National Hurricane Center
- Time-stamped photos and video from before flooding arrived
- Engineering analysis of damage patterns consistent with wind vs. water
- Neighbor accounts of damage progression
- Insurance industry standards for wind/flood allocation
Coastal Florida policyholders facing hurricane losses should engage an experienced engineer early, ideally before the insurer's adjuster locks in a wind-vs-flood classification.
Large-loss claims: different procedures, more scrutiny
Florida insurers handle large losses (typically defined as over $100,000–$250,000 depending on the carrier) differently from routine claims. What changes:
- Senior adjusters with more experience and authority handle the file
- Examination Under Oath (EUO) requests become routine, not exceptional
- Engineers are retained by the insurer to evaluate causation and scope
- Sworn proof of loss requests are pursued more aggressively, with specific dollar values demanded
- Recorded statements from the policyholder, family members, and witnesses are sought
- Reservation of rights letters reserve the insurer's right to add defenses later
The procedural sophistication of large-loss handling means policyholders facing one are almost always better off with legal representation. Statements made carelessly at an EUO, a Proof of Loss that overstates or understates the claim by a meaningful margin, and concessions about causation can each defeat a claim that would otherwise be paid in full.
Commercial property claims and business interruption
Commercial property claims add complexity that residential claims rarely involve:
Business Personal Property (BPP)
Inventory, equipment, furniture, fixtures, and improvements made by the tenant. Valuation often involves cost basis, depreciation schedules, and replacement timelines. BPP claims frequently involve sublimits the policyholder didn't know existed.
Business Interruption (BI)
Lost income and continuing expenses during the period of restoration. BI coverage requires detailed financial documentation: historical revenue, profit margins, expense categories, and projections of what the business would have earned absent the loss. The "period of restoration" is itself disputed — insurers tend to argue for a shorter period than policyholders.
Extra Expense (EE)
Additional costs to keep the business operating despite the loss: temporary location, expedited shipping, overtime labor, equipment rental. EE has its own sublimits and proof requirements.
Contingent Business Interruption
Lost income when a supplier or customer's property damage interrupts your business. Less common but important for businesses dependent on specific upstream or downstream parties.
Commercial claim disputes frequently end up in federal court under diversity jurisdiction (when the insurer is in a different state than the insured) rather than state court. The procedural rules, discovery scope, and motion practice all change in federal court — another reason commercial claims tend to benefit from experienced counsel.
Subrogation: when the insurer goes after someone else
When a third party causes the loss (a contractor's negligent work, a neighbor's tree falling on your property, a product manufacturer's defective equipment), your insurer pays your claim and then "subrogates" — pursues recovery from the responsible third party.
Subrogation can complicate your direct claim in several ways:
- The insurer may want you to assign your rights and cooperate with their subrogation effort
- You may have separate claims (for your deductible, for uncovered losses) that ride alongside the subrogation
- Statements you make during the insurer's subrogation investigation can be used against you in your own claim
- Settlements in subrogation may extinguish related claims you haven't fully pursued
For losses involving clear third-party fault and substantial uninsured damage, having your own attorney coordinate with (not just defer to) the insurer's subrogation effort can capture recovery that would otherwise go entirely to the insurer.
Expert witness battles in complex claims
Most complex Florida property damage claims that go to litigation become expert witness battles. The insurer hires engineers, contractors, accountants, and meteorologists; the policyholder hires the same categories of experts in opposition. The case often turns on which experts the judge or jury finds more credible.
The categories of experts that show up most often:
- Causation experts — engineers and meteorologists explaining what caused the damage (wind vs. flood, freeze vs. wear-and-tear, fire origin)
- Scope and cost experts — contractors and estimators detailing what repairs are needed and what they actually cost
- Forensic accountants — calculating business interruption losses for commercial claims
- Public adjusters — valuing the loss and translating between insurance and construction terminology
- Appraisers — establishing actual cash value, replacement cost, and depreciation
The quality of experts available to your case is often determined by whether you have legal representation. Solo policyholders rarely have the contacts and credibility to retain the same caliber of expert that defense firms regularly use.
When complex claims go to court
Complex Florida property damage cases that don't settle through negotiation, mediation, or appraisal proceed to litigation. The basic path:
- Civil Remedy Notice (when bad faith is alleged) — 60-day cure period under Fla. Stat. § 624.155
- Complaint filed — in state circuit court for most cases, federal court for diversity-jurisdiction cases
- Discovery — document production, interrogatories, depositions of policyholder, adjusters, and experts (often 6–12 months)
- Expert reports and depositions — each side's experts submit reports and are deposed
- Motion practice — summary judgment motions, Daubert challenges to expert testimony, motions in limine
- Mediation — court-ordered mediation in most cases, often the final settlement opportunity before trial
- Trial — most complex claim cases that reach this stage settle on the courthouse steps; a small percentage actually try
The full timeline from suit filing to resolution typically runs 12–24 months. Cost varies widely depending on expert work and motion practice. Most plaintiff attorneys handle complex property damage cases on contingency (33–40% of recovery), with costs advanced and reimbursed from the recovery.
Strategy for complex Florida property damage claims
If your claim is complex, the practical strategy differs from a simple claim:
- Get legal counsel early. Complex claims punish mistakes more severely than simple ones. Statements at an EUO, sloppy Proof of Loss documents, careless concessions about causation can each be fatal.
- Build your expert team early. Engineers, public adjusters, forensic accountants — the insurer is already building theirs. Yours need to be at the same level.
- Document everything obsessively. In complex claims, the evidentiary record built in the first 60 days often determines the outcome.
- Don't accept partial classifications. If the insurer is calling the loss flood when it's substantially wind, push back immediately with evidence rather than accepting the framing.
- Use Florida's procedural tools. The Civil Remedy Notice, free DFS mediation, the appraisal clause — each is a tool that creates leverage in complex disputes.
- Be prepared for the long timeline. Complex claims that go to litigation take 12–24 months to resolve. Plan financially and emotionally for that arc.



